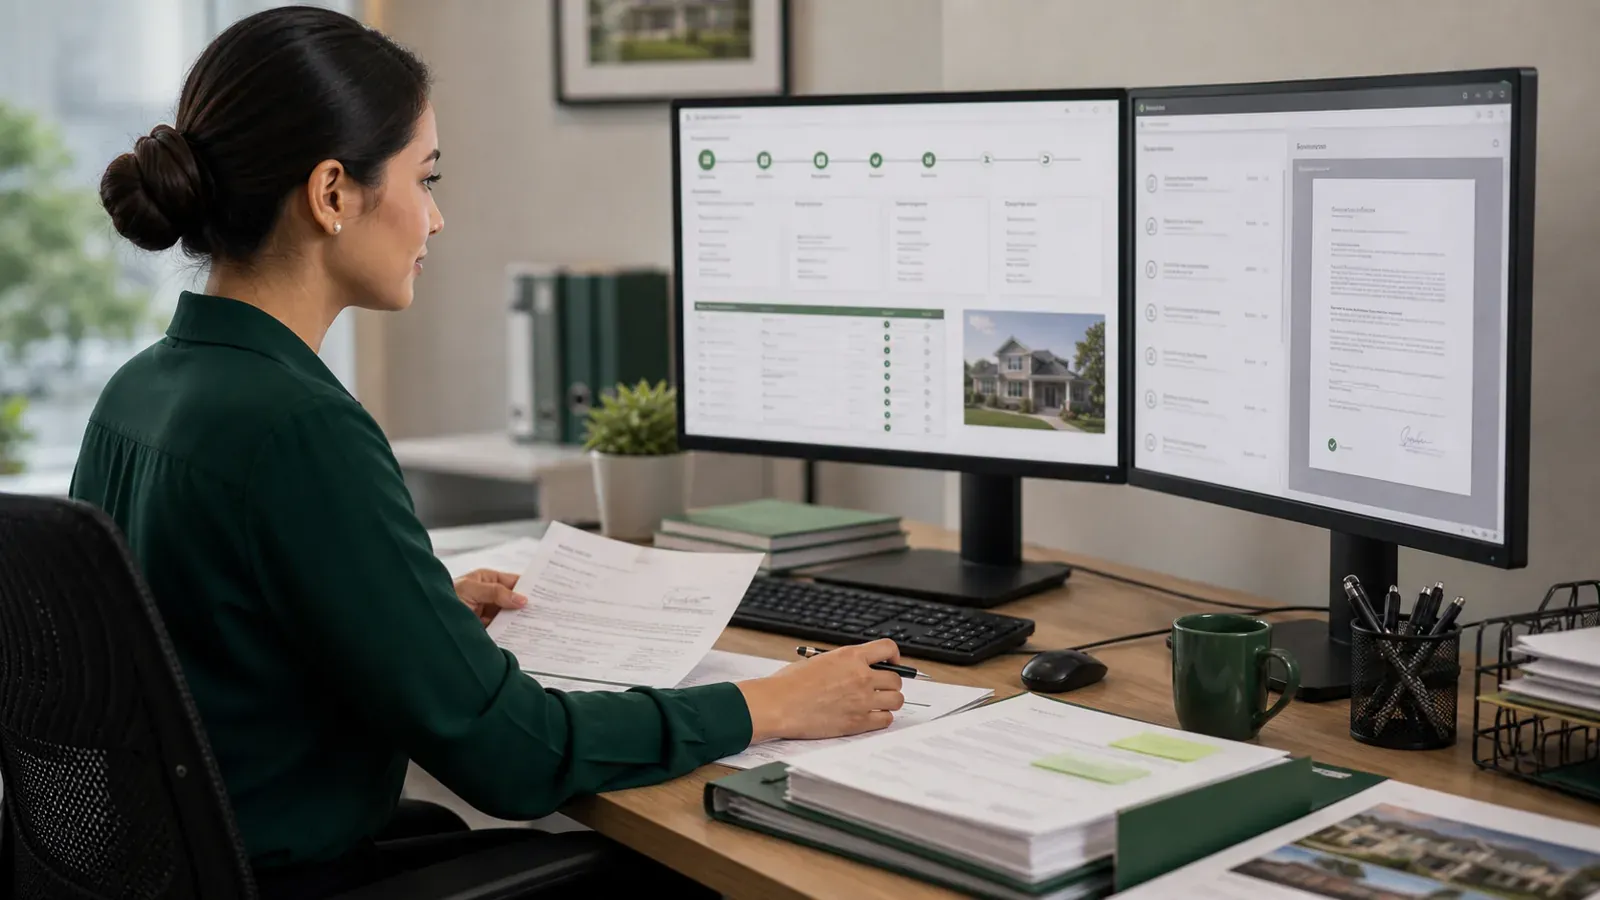
- Document chasing and status updates are the biggest time savers for most loan officers.
- Unlicensed staff should not take applications or offer or negotiate loan terms. Your compliance team sets the exact boundaries.
- Borrower data is sensitive. Use separate logins, least-privilege access and your company's security policies.
What does a mortgage virtual assistant do?
Document collection
- Sending needs lists and reminders for pay stubs, bank statements, tax returns and IDs
- Checking uploads for completeness and legibility
- Labelling and filing documents in the loan origination system or document portal
Pipeline and CRM management
- Updating loan milestones in the pipeline report
- Logging conversations and next steps in the CRM
- Flagging files that are stalled or close to key dates such as lock expirations and closing
Communication
- Sending scheduled status updates to borrowers and realtor partners
- Coordinating appraisal, title and closing schedules
- Answering routine “where are we?” questions using approved templates
Marketing and relationships
- Running past-client and realtor-partner email campaigns
- Scheduling social posts and co-marketing material for compliance review
- Tracking referral sources
What should stay with a licensed loan officer?
Under the SAFE Act and state licensing rules, taking a residential mortgage loan application and offering or negotiating loan terms are licensed activities. In practice that means a VA should not:
- Take a loan application or collect application information as an interview
- Quote, discuss or negotiate rates, fees or loan terms
- Recommend loan programs or advise on qualification
Every lender draws these lines slightly differently, so confirm task boundaries with your compliance team before you delegate.
How do you protect borrower data with a VA?
Borrower files contain non-public personal information, so follow your company's information security program. At a minimum: separate user accounts, two-factor authentication, access limited to the systems the VA needs, a confidentiality agreement, no downloads to personal devices, and same-day removal of access when the engagement ends. Our VA security checklist walks through each step.
How do loan officers use VAs alongside processors?
Processors handle the loan file through underwriting. A VA supports the loan officer before and around that work — chasing documents, updating partners and keeping the pipeline clean — so processors receive more complete files and the loan officer spends more time originating.
Frequently asked questions
Can a virtual assistant take a mortgage application?
No. Taking a residential mortgage loan application is a licensed activity. A VA can send document requests and organise files, but the application itself must be handled by a licensed loan officer.
Can a mortgage VA work in my LOS?
Often yes, with their own user account and limited permissions set by your company. Confirm with your IT and compliance teams which roles they allow.
What is the difference between a loan officer assistant and a processor?
A loan officer assistant supports the loan officer with documents, communication and pipeline updates. A processor prepares the full loan file for underwriting and works the conditions.
Do mortgage virtual assistants work U.S. hours?
They can. For borrower and realtor communication, part of the VA's day should overlap with your business hours.
Owner of Smart VA Solutions. Premanshu leads a team of real-estate-trained virtual assistants, transaction coordinators and marketers supporting U.S. realtors, brokerages and mortgage teams.
Comments
Be respectful. Comments are reviewed before they appear.
Leave a comment